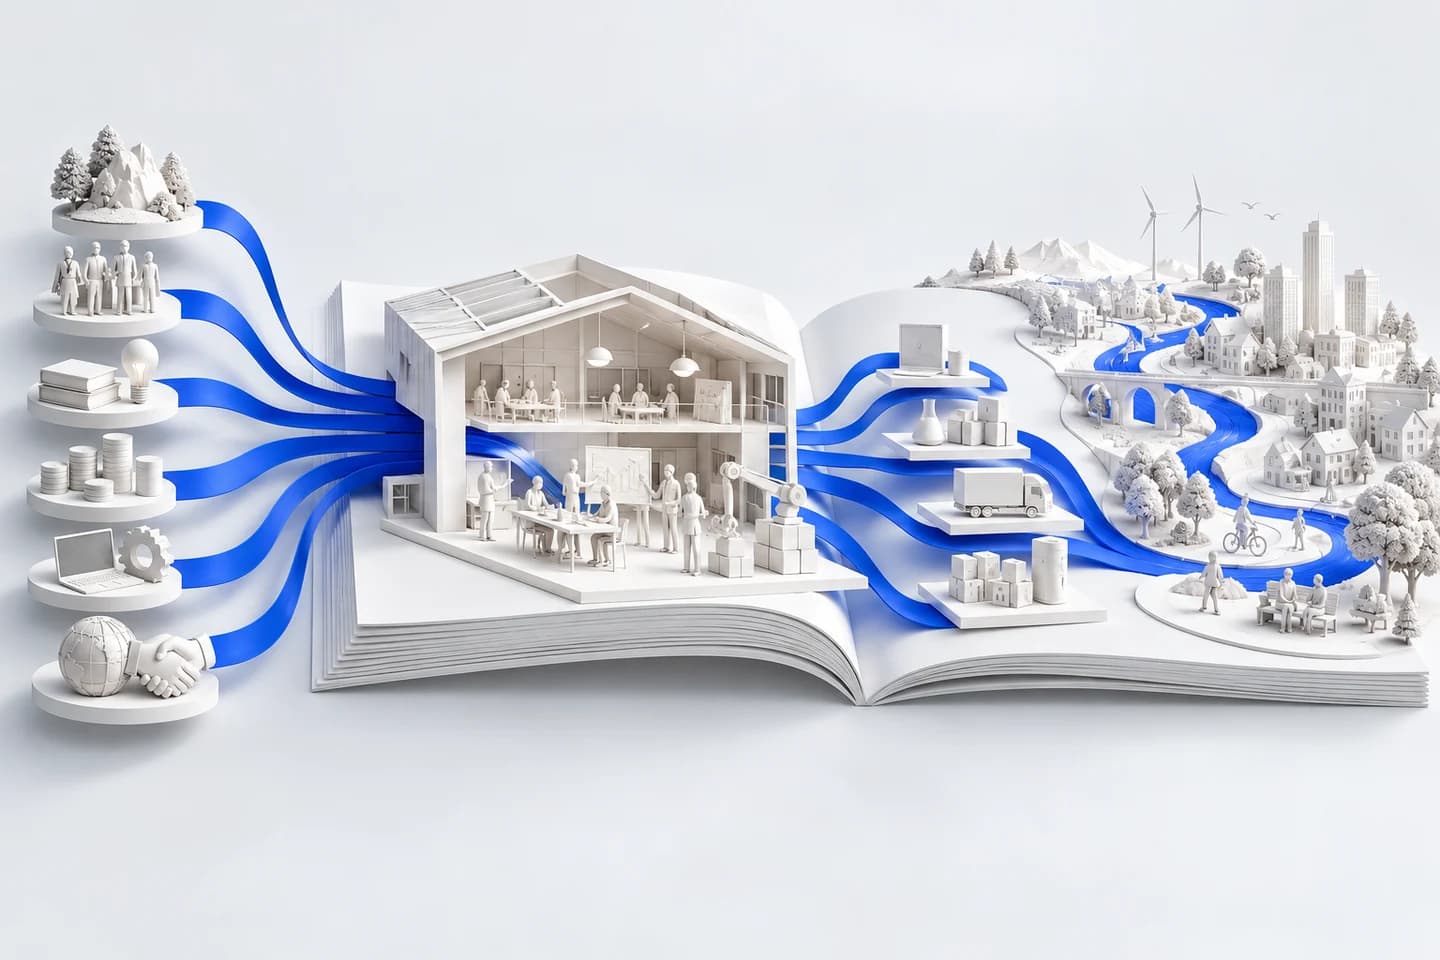
Every large Indian integrated report now has a value creation model. We scored ten FY 2025-26 models against what the Integrated Reporting Framework actually asks for. All ten put numbers against their inputs. None shows a trade-off between capitals, and only one keeps outputs and outcomes cleanly apart.
In this article
 In short
Key takeaways
- The Framework defines the business model as the system that turns inputs, through business activities, into outputs and outcomes (paragraph 4.11). It suggests a simple diagram, but the diagram is a readability aid, not a requirement.
- Outputs are products, services, by-products and waste. Outcomes are the positive and negative consequences for the capitals (paragraphs 4.18 and 4.19). Several Indian models put production volumes or counts of assets under "outcomes".
- All ten models we scored quantify inputs by capital. None of the ten shows a trade-off between capitals, which paragraph 5.8 says an integrated report should disclose.
- Tata Steel (pp. 20-21) scored highest at 8 out of 12: a separate output column, an outcome column that includes emissions and injury rates, and symbols marking which boundary each metric uses.
- The commonest faults are unlabelled boundaries (L&T's model uses standalone figures without saying so), adjusted numbers that can't be traced to the statements, and natural capital shown only through avoided emissions.
- SEBI's February 2017 circular listed the six capitals and seven guiding principles but said nothing about a business model diagram. The format is a company choice.
Every large Indian integrated report now carries a value creation model, usually a two-page spread with the six capitals down one side and a set of stakeholder icons down the other. We read the model in ten FY 2025-26 reports and scored each one against what the Integrated Reporting Framework actually asks a business model disclosure to do. The inputs are almost always well counted. The rest of the diagram is where the reports part ways with the Framework.
All ten models quantify their inputs by capital, and none of the ten shows a trade-off between capitals. Only one, Tata Steel's, keeps outputs and outcomes properly apart and lets the outcome column carry bad news.
What the Framework asks for, paragraph by paragraph
- InputsWhat do we draw on?Capital, people, knowledge, relationships, assets and nature.
- ActivitiesWhat do we do?How we transform resources and differentiate the business.
- OutputsWhat do we produce?Products, services, by-products and material waste or emissions.
- OutcomesWhat changes?Positive and negative effects on the capitals, inside and outside the business.
Framework paragraphs 4.11–4.21. Simplified explanation, not a prescribed diagram. Outcomes feed back into the capitals over time.
The Integrated Reporting Framework (January 2021 revision, now maintained by the IFRS Foundation) never uses the phrase "value creation model". It talks about a business model, and it describes the process around it in two places.
Paragraph 2.23 places the business model at the core of the organisation. It draws on the capitals as inputs and, through business activities, converts them into outputs. Those activities and outputs then lead to outcomes, which are effects on the capitals. Figure 2 on page 22 draws this as the familiar diagram, with the external environment, governance, risks and opportunities, strategy, performance and outlook wrapped around the business model.
Paragraph 4.11 gives the definition: a business model is a system that transforms inputs, through business activities, into outputs and outcomes. Paragraph 4.12 asks the report to describe each of those four elements. The detail sits in the paragraphs that follow:
| Element | Framework paragraph | What it asks for |
|---|---|---|
| Inputs | 4.14 to 4.15 | Key inputs and how they relate to the capitals, focusing on what's material; not an exhaustive list. May discuss the trade-offs that influence the choice of inputs |
| Business activities | 4.16 to 4.17 | How the company differentiates itself, earns revenue after the point of sale, innovates and adapts |
| Outputs | 4.18 | Key products and services, plus by-products and waste (including emissions) where material |
| Outcomes | 4.19 to 4.21 | Internal and external consequences for the capitals, positive and negative, presented in a balanced way, including effects up and down the value chain |
| Trade-offs | 5.8 | Important trade-offs between capitals, over time, and between capitals the company owns and those it doesn't |
Paragraph 4.13 lists features that make the description more readable. A simple diagram is one of them, alongside a clear explanation and links to strategy, risks and opportunities, and performance, including KPIs and financial figures. So the diagram is a suggestion, and connection is the point. And paragraph 2.17 says a report doesn't have to use the six capital categories at all; they're a checklist to make sure nothing material is missed.
The Framework's own worked example uses a carmaker. Its output is cars. Its positive outcomes include profits, dividends, taxes and a stronger brand. Its negative outcomes include fuel depletion, poorer air quality and pressure on its social licence. That example shows how far most Indian models are from the Framework. They tend to list the cars under "outcomes" and leave the air quality out.
What SEBI said
SEBI's circular of 6 February 2017 advised the top 500 listed companies that they "may" adopt integrated reporting from FY 2017-18. It reproduced the seven guiding principles, listed the six capitals and linked to the 2013 version of the Framework. It said nothing about a business model diagram, and it didn't prescribe a format. As we explained in our guide to integrated reporting in India, that circular now sits among those rescinded by the January 2026 LODR master circular. The value creation model is entirely the company's own design choice, which is why the ten we read look so different.
How we scored the ten
We took ten FY 2025-26 integrated reports the site has already reviewed, opened each PDF at its model page and scored six questions. Each answer earned 2 for yes, 1 for partly and 0 for no, for a maximum of 12.
- Are the inputs quantified for each capital the company uses?
- Are outputs separated from outcomes, and do the outcomes describe effects on the capitals?
- Is any trade-off between capitals shown?
- Does the model link to strategy, risks and KPIs?
- Can its figures be tied to the financial statements and the BRSR, with the boundary stated?
- Does it read as this company's business model, or as a decorative wheel that would fit any company?
Page numbers below are the printed page numbers in each report.
The scorecard
| Company | Model pages | Inputs quantified | Outputs vs outcomes | Trade-offs | Strategy, risk, KPI links | Ties to statements and BRSR | Real business model | Score /12 |
|---|---|---|---|---|---|---|---|---|
| Tata Steel | 20-21 | Yes | Yes | No | Partly | Partly | Yes | 8 |
| HUL | 10-13 | Yes | Partly | No | Partly | Partly | Yes | 7 |
| Infosys | 48-49 | Yes | Partly | No | Partly | Partly | Yes | 7 |
| Hindustan Zinc | 72-75 | Yes | Partly | No | Partly | Partly | Yes | 7 |
| Bharti Airtel | 36-37 | Yes | Partly | No | Yes | Partly | Partly | 7 |
| Mahindra | 39-40 | Yes | Partly | No | Partly | Yes | Partly | 7 |
| HDFC Bank | 60-61 | Partly | Partly | No | Yes | Partly | Partly | 6 |
| L&T | 176-177 | Yes | No | No | Partly | Partly | Yes | 6 |
| TCS | 42-43 | Yes | No | No | Partly | Partly | Yes | 6 |
| NTPC | 38-39 | Yes | Partly | No | Partly | Partly | Partly | 6 |
The spread of scores is narrow. Nobody gets above 8, and the column that drags everyone down is the same one.
Key number: 0 of 10 — the number of models that show a single trade-off between capitals, though paragraph 5.8 of the Framework asks for the important ones
What the better models do differently
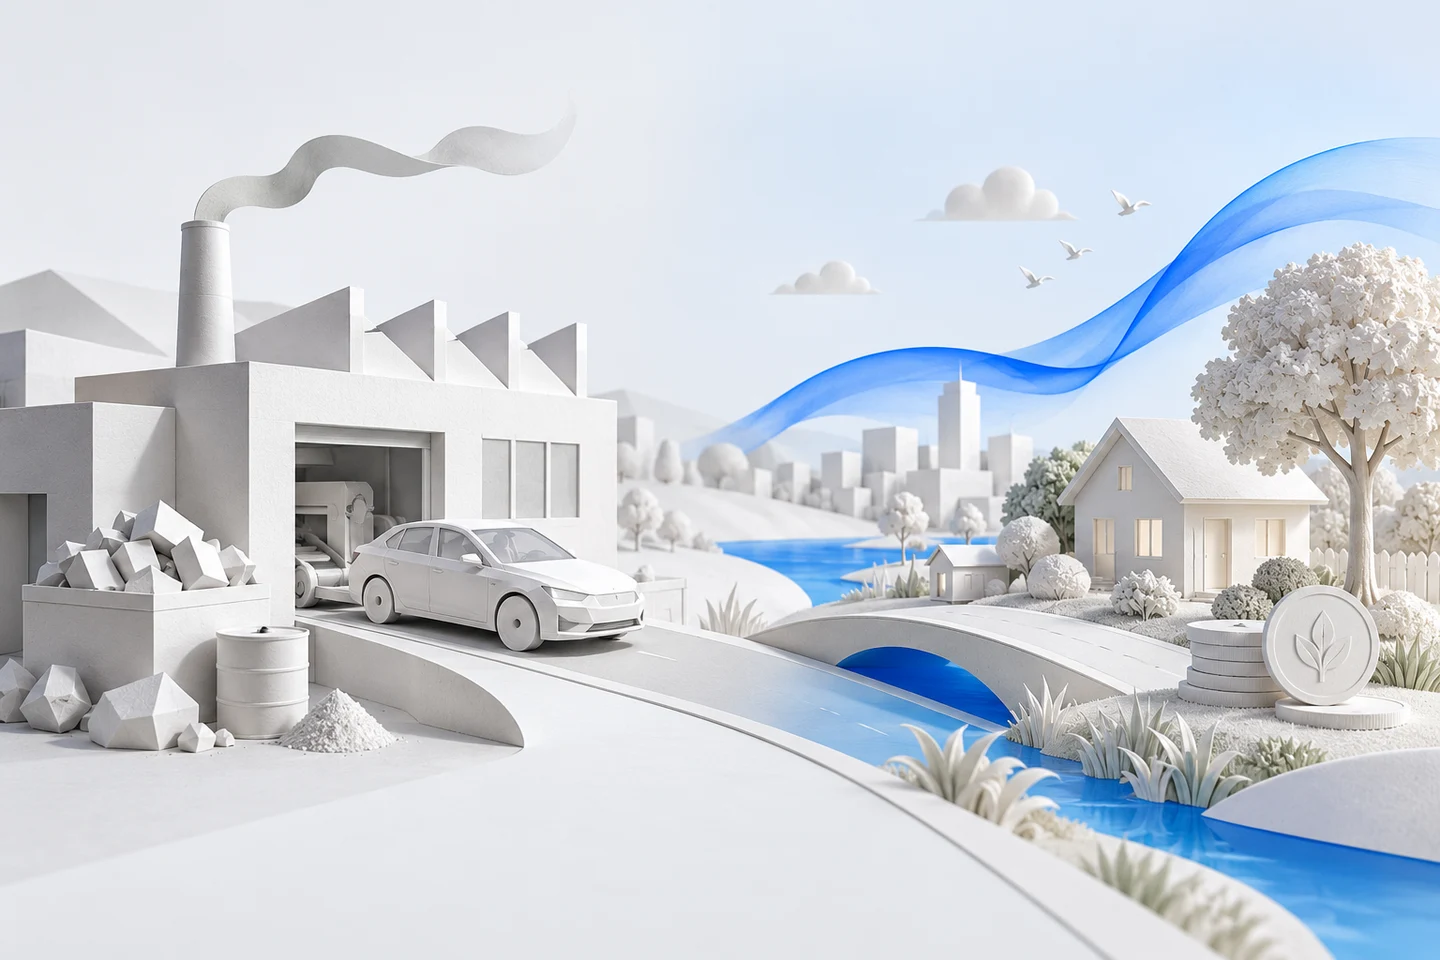
- Cars produced and delivered
- Services supplied
- By-products and waste
- Emissions, where material
- Profits and cash flows
- Customer satisfaction
- Changes in employee safety
- Resource depletion and air-quality effects
Keep the two ideas in separate columns. Describe both positive and negative consequences.
Illustrative carmaker example. Framework paragraphs 4.18–4.19. The artwork is conceptual and does not show actual company data.
Each of the stronger models has one habit the others could borrow.
Tata Steel's model (pp. 20-21) runs in four columns: input, value chain, output, outcome. The output column holds what a steelmaker actually produces: 31.67 million tonnes of production, 31.97 million tonnes delivered and more than ₹9,100 crore of revenue from by-products. The outcome column then carries the effects, and it doesn't hide the uncomfortable ones. CO2 intensity of 2.22 tonnes per tonne of crude steel sits there, next to effluent discharge, SOx and NOx intensity and a lost-time injury frequency rate of 0.48. Two symbols tell the reader whether a metric covers the group's steelmaking entities or Tata Steel Limited alone. That's the outputs-versus-outcomes distinction and the boundary discipline on one spread.
Mahindra (pp. 39-40) is the best at saying what its numbers are. A line on the page states that the model represents consolidated inputs and outputs. The natural capital footnote defines the boundary as all India operations, which it says cover more than 90% of the environmental footprint. It also points to the sustainability report for assured numbers. The ₹93,096 crore of equity attributable to owners matches the consolidated figure elsewhere in the report.
HDFC Bank (pp. 60-61) has the most connected model. The left page ties CEO priorities, material topics, risk management and strategic pillars to the business activities. The right page gives inputs and outcomes for each capital. It then keys each capital by number to the ten risks listed along the foot of the spread, from credit risk to spill-over risk from subsidiaries. A reader can see that natural capital is exposed to credit and climate risk without hunting for it.
Bharti Airtel (pp. 36-37) links outwards by page reference. The spread sends the reader to the MD&A on page 156 and to risks and opportunities on page 54. A footnote states the boundary for each capital: financial capital on a standalone basis and the rest for Indian operations, excluding Indus Towers, Airtel Payments Bank and Beetel Teletech.
HUL (pp. 10-11) footnotes its own definitions. Trade working capital excludes cash and current investments, and its 110.9% return on capital employed is flagged as standalone. Its ₹49,008 crore of net worth agrees with share capital plus other equity in the ten-year table on pages 18 to 19. The facing spread, "Interplay of Capitals" (pp. 12-13), is the nearest any of the ten gets to showing how capitals affect each other. It's a six-by-five grid with an example in every cell.
In practice: before the design brief goes out, give every number on the model a source line in a working file: the statement, note or BRSR principle it comes from, and its boundary. If a figure has no source line, it doesn't go on the page.
Mistakes that keep turning up
Build a new production line to expand capacity.
More manufactured capacity and future financial returns.
More water use, near-term emissions or pressure on local resources.
Illustrative scenario, not a claim about a reviewed company. Framework paragraph 5.8 asks for important trade-offs between capitals and over time.
No trade-offs anywhere. HUL's interplay grid is the closest attempt, and every one of its 30 cells describes a capital helping another. Not one describes a cost. A mining company that draws 24.18 cubic metres of water per tonne of metal (Hindustan Zinc, p. 72) or a power producer adding coal capacity faces real choices between financial, natural and social capital. The models don't show them.
One column for two ideas. TCS heads its right-hand column "Outputs and Outcomes" (pp. 42-43) and fills it with a mix: patents granted, $40.7 billion of total contract value, 66 clients above $100 million, a 1.58 power usage effectiveness. It's the cleanest spread to read, and it scores lower here only because it doesn't make the distinction the Framework asks for. L&T (pp. 176-177) goes from input straight to output, with greenhouse gas emissions and return on net worth in the same column as kilometres of bridges built.
Outcomes that are slogans. NTPC (pp. 38-39) has a separate outcomes column, but its entries read "Powering the nation reliably" and "Operating with integrity and trust". Infosys (pp. 48-49) does better with stakeholder-specific statements such as profitable growth and safe workplaces, but none of them carries a number. An outcome that can't be measured can't be compared next year.
The model is the one page in the report where finance, sustainability and strategy have to agree on the same numbers.
Natural capital told through avoided emissions. NTPC's natural capital output is 31.5 million tonnes of avoided CO2 (pp. 38-39). Its Scope 1 emissions of 358.00 million tCO2e appear on page 76, not on the model. Airtel's model shows 349,120 tCO2e avoided and a 17% reduction (pp. 36-37). Its absolute Scope 1 and 2 total of 911,950 tCO2e sits on pages 52 to 53. Paragraph 4.18 says waste and emissions are outputs to discuss when material. For a coal-heavy utility they're the most material output it has.
Unlabelled boundaries and adjusted numbers. L&T's model shows turnover of ₹1,53,680 crore and an order book of ₹6,13,235 crore. Those are standalone figures (p. 44), but the model doesn't say so, and the strategy section reports group revenue of ₹2,85,874 crore (p. 29). NTPC's financial capital mixes group-level revenue and profit with a net worth of ₹2,03,023.74 crore that, per its footnote, excludes the fly ash utilisation reserve and other comprehensive income items. Airtel's model uses net profit before exceptional items. Each choice may be defensible, but a reader can't reconcile any of them to the balance sheet without help.
Unit errors. Hindustan Zinc's outputs band (pp. 74-75) gives zinc output as "851 tonnes", while the outcomes table on the same page gives refined metal production of 1,048 kt on the same spread. Zinc and lead of 851 and 197 add to exactly 1,048, so the unit should be kilotonnes. Nobody checks the model with the care given to the statements, because nobody owns it.
How to build yours
- Explain the businessWrite how inputs become revenue and cash before drawing the model.
- Choose material capitalsUse the six-capital categories as a checklist; adapt them where useful.
- Source every metricRecord the statement, note or BRSR line, year, unit and boundary.
- Separate outputs and outcomesGive products and consequences their own headings.
- Show the difficult effectsInclude material negative consequences and real trade-offs.
- Connect and challengeLink strategy, risks and KPIs; ask an outsider to explain the business from the model.
Editorial workflow distilled from this article. Use material capitals and a clearly stated reporting boundary; flag exceptions.
We'd run it in this order, with the finance team and the design team in the same room.
- Write the business model as a paragraph first. If the CFO can't describe in 150 words how the company turns its inputs into revenue and cash, a diagram won't fix it. Paragraph 4.16 gives the prompts: differentiation, revenue after the point of sale, innovation and adaptability.
- Pick the capitals that matter. Use the six as a checklist, then merge or rename where it reflects how you're actually run. Infosys combines natural and manufactured capital, and the Framework allows it.
- Choose three to five inputs per capital and source each one. Every financial figure should match a line in the statements on the same basis. Every non-financial figure should match the BRSR or the assured sustainability data. State the boundary on the page.
- Separate outputs from outcomes in the design itself. Two columns, two headings. Outputs are what you make and what you emit. Outcomes are what changed for customers, employees, communities, the environment and shareholders.
- Put at least one negative outcome on the page. Emissions, water drawn, injuries, attrition. If it's material enough for the BRSR, it's material enough for the model.
- Name one or two real trade-offs. A capex programme that raises emissions before it lowers them is a trade-off over time. Automation that cuts headcount is a trade-off between human and financial capital. A sentence each is enough.
- Key the model to risks, strategic priorities and KPIs. HDFC Bank's numbered risk keys and Airtel's page references cost almost no space.
- Test it on someone outside the company. If they can't explain how the company makes money from the spread alone, simplify it.
For agencies, the useful brief is the source file from step 3, not a mood board. The design should follow the data, and it can't do that if the data arrives last. Our piece on moving from an annual report to an integrated report covers the wider sequence.
What this means for CFOs and IR teams
The model is the one page in the report where finance, sustainability and strategy have to agree on the same numbers.
- Own it in finance. Put the model's figures through the same tie-out as the financial highlights. Most of the errors above would have been caught by a reviewer with the statements open.
- Align it with the BRSR. Natural, human and social capital inputs should come from the same data as BRSR Principles 3, 6 and 8. If you're preparing for BRSR Core assurance, you already have assured numbers to use.
- Decide the boundary once. Consolidated, standalone or India operations. Pick one, say it on the page, and flag any exceptions the way Tata Steel and Mahindra do.
- Don't rebuild it every year. Keep the structure stable so that outcomes can be compared over time. Consistency over time is one of the seven guiding principles SEBI's circular reproduced.
- Ask the audit committee to look at it. It isn't audited, but it's the page analysts photograph. A wrong unit there costs more credibility than one in a note.
If you're starting next year's report now, take last year's model and write down, against each figure, the page or BRSR line it came from. The figures you can't source are the place to start.
Frequently asked questions
What is a value creation model in an integrated report?
It is the diagram, usually a two-page spread, that shows the company's business model as the Integrated Reporting Framework describes it: inputs from the capitals the company depends on, the business activities that transform them, the outputs (products, services, by-products and waste), and the outcomes, meaning the positive and negative effects on the capitals over the short, medium and long term.
What is the difference between outputs and outcomes?
Outputs are what the business produces: products, services, by-products and waste, including emissions (Framework paragraph 4.18). Outcomes are the consequences of those activities and outputs for the capitals, both positive and negative, inside and outside the company (paragraph 4.19). Tonnes of steel delivered is an output. A change in customer satisfaction, employee injury rates or local air quality is an outcome.
Is a value creation model mandatory in India?
No. Integrated reporting itself is voluntary in India. SEBI's circular of 6 February 2017 advised the top 500 companies to consider it from FY 2017-18 and pointed to the IIRC Framework, but it prescribed no format and did not mention a business model diagram. The Framework suggests a simple diagram as one feature that makes the business model easier to read (paragraph 4.13).
Does a value creation model have to use all six capitals?
No. Paragraph 2.17 of the Framework says a report doesn't have to adopt the six categories or be structured around them, and paragraph 2.16 accepts that not every capital matters to every company. Infosys, for example, combines natural and manufactured capital into one row. What the Framework wants is that no capital the company materially uses or affects is overlooked.
What are trade-offs between capitals?
They are choices where gaining in one capital costs another, or where a gain now costs more later. Paragraph 5.8 of the Framework gives examples: creating jobs through an activity that harms the environment, or choosing a course of action that pays back sooner but less. A report should disclose the important trade-offs that influence value creation over time.
Should the figures in the value creation model match the financial statements?
Yes, or the model should say why they don't. Several Indian models do match: TCS's ₹107,240 crore net worth, Infosys's ₹92,852 crore net assets and HDFC Bank's ₹5,62,900.91 crore shareholders' funds all agree with figures elsewhere in their reports. The problems arise when a model silently uses standalone figures, adjusted figures or profit before exceptional items without labelling the basis.
Sources
- International Integrated Reporting Framework, January 2021 — IFRS Foundation
- SEBI circular SEBI/HO/CFD/CMD/CIR/P/2017/10, Integrated Reporting by Listed Entities (6 February 2017) — SEBI
- Tata Consultancy Services, Integrated Annual Report 2025-26 — TCS
- Infosys, Integrated Annual Report 2025-26 — Infosys
- HDFC Bank, Integrated Annual Report 2025-26 — HDFC Bank
- Larsen & Toubro, Integrated Annual Report 2025-26 — Larsen & Toubro
- Hindustan Unilever, Integrated Annual Report 2025-26 — Hindustan Unilever
- Hindustan Zinc, Integrated Annual Report FY 2025-26 — Hindustan Zinc
- Tata Steel, Integrated Report and Annual Accounts 2025-26 — Tata Steel
- Mahindra & Mahindra, Integrated Annual Report 2025-26 — Mahindra & Mahindra
- NTPC, Integrated Annual Report 2025-26 — NTPC
- Bharti Airtel, Integrated Report and Annual Financial Statements 2025-26 — Bharti Airtel